A sustainability report treated as a campaign becomes a liability
In many companies, the sustainability report is still born in a meeting where someone says it must be ready for the April event, and from then on the communication calendar's deadline starts to dictate the content. The result tends to follow a recognizable pattern: an opening page with a photo of seedlings being planted and not a word on how many survived; a promise of carbon neutrality by 2050, with no emissions inventory or plan to support it; a "100% sustainable" seal stamped on packaging that the report itself shows to be partly recyclable; a diversity campaign illustrated by a board in which nobody resembles the people pictured. Each of these items, on its own, looks like an editorial slip, but together they show a document assembled from the outside in, with the image in front and the data running behind.
The problem already has a name
Greenwashing is the best-known term and describes communicating environmental performance better than it really is, but the family is large. Socialwashing does the same with human rights, labor relations, diversity and community impact, and greenhushing appears when a company, afraid of being held to account, prefers to hide what it actually already does. The mechanism is always the same: the narrative moves faster than the evidence, and a report produced as a one-off communication action creates this gap almost unintentionally. Nobody needs to act in bad faith to get there. It is enough to pick only the good news, publish indicators without a historical series, announce targets with no deadline and no owner and let the photograph take the place of the result, because there is no process behind it to prevent this.
Readers do not read it as a campaign
Investors, banks, corporate customers, insurers and oversight bodies read the report to make decisions and cross-check it against other sources, such as financial statements, environmental licenses, infraction notices and what the press published during the year. In Brazil, misleading advertising is already addressed by the Consumer Protection Code, Conar has its own rules for sustainability claims in advertising (Annex U of its code) and CVM Resolution 193 brings listed companies' reporting closer to the ISSB's IFRS S1 and S2 standards, although adoption is now voluntary, according to CVM. In this environment, claiming something without backing stops being merely image damage and can become a legal challenge, loss of access to credit or loss of contracts with customers who audit their own supply chain.
A sustainability report is a management report, and a financial management one
Behind every serious report there is a simple question that the board must be able to answer with data: what are we doing to keep existing, producing, having access to inputs, maintaining a healthy workforce and generating jobs, on this planet and in these communities, in a way that can last? This is a question about business continuity and, therefore, about money. A planet that changes in several directions at once, with physical, chemical and climate changes that already affect water availability, rainfall patterns, operating temperature, insurance prices, energy costs and the health of those who work, turns socio-environmental risk into financial risk, and that is exactly why ISSB standards treat sustainability as relevant information for those who invest and lend. A report that cannot show how the company sees these risks and opportunities, how much they weigh on cash, investments and targets, and what is being done to reduce or seize them serves, at most, as a shop window.
To have that answer, the report needs to be the visible result of a cycle that runs all year, with data that has an owner and a method, material topics defined from listening to stakeholders, targets tied to strategy and budget, internal controls and, when the moment calls for it, external verification. GRI and ISSB do not ask for pretty text, they ask for traceability, and when communications receives the material in March, almost nothing can be done beyond embellishing.
If the logic is communication, communication needs to understand the subject
Many companies, for lack of maturity or budget, will treat the report as a communication piece for one more cycle, and it is possible to start that way, as long as those who write, edit and lay it out have at least a minimum of sustainability and ESG literacy. Without it, mistakes that seem small and are serious appear: an SDG confused with a performance indicator; a commitment presented as a target; one year's data sold as a trend; "carbon neutral" claimed with no inventory and no offsetting criteria; emissions scopes mixed up; "in accordance with GRI" written where GRI was only used as a reference (the difference exists and is verifiable); materiality ignored or treated as a word cloud. Each slip moves the document away from the standards the company says it follows, and a reader with a technical eye notices within minutes.
But the literacy of the communications team solves only part of the problem, because the report depends on people from many areas. When a company hires a consultancy to run the cycle, the work really pays off if it names focal points: people from each area (operations, finance, legal, human resources, procurement, environment, health and safety, community relations) who will be the consultancy's counterparts, will answer for the quality and timing of the data and will take back to their teams what is decided. These focal points cannot be a name put in a spreadsheet for convenience. They need training on the adopted standards, on how an indicator is built and on the difference between data, evidence and narrative, and they need time formally set aside in their calendar for it.
The same goes for the ESG Committee, which only works as a decision body when its members have been prepared for the seat, with ongoing training and a composition that includes people from different areas and profiles, instead of always reproducing the same group that already decides everything else. A committee without literacy approves what it is shown, and a committee without diversity sees only part of the risks.
Finally, and perhaps the hardest, managers across the areas need to be inside the process, and not merely receive, at the end, a request for data. Each of them must set targets for their area, follow them through the year, measure results with a method and report what happened, including when the target was not met, and for that they also need literacy. A water consumption reduction target set by the operations director, tracked monthly by their team and presented by them to the Committee carries a very different weight from a sentence written by communications from a spreadsheet sent in a hurry.
Where to start
It is worth bringing communications into the design of the cycle, and not only into the delivery; defining who owns each piece of data; training focal points and the ESG Committee before the cycle opens; asking each manager to sign off on their targets and present their results; and doing the final line-by-line review with whoever knows the number. If the report has to go out with gaps, it is better to say so, with what is missing and the expected date for improvement, because admitting what is not yet good is the most effective defense against washing. An honest, modest report that ages well is worth more to the company than a beautiful, inflated one that needs explaining the following year.
Talk to KICK
KICK Group works on socio-environmental communication and stakeholder engagement, including the design of the data cycle and the training of focal points and committees for sustainability reporting. If your company wants to move on from the campaign-style report, it is worth talking.
Write to contato@kickgroup.com.br. Informational text, updated as of November 9, 2026. Disclosure rules change and must be confirmed at the sources.
Keep reading
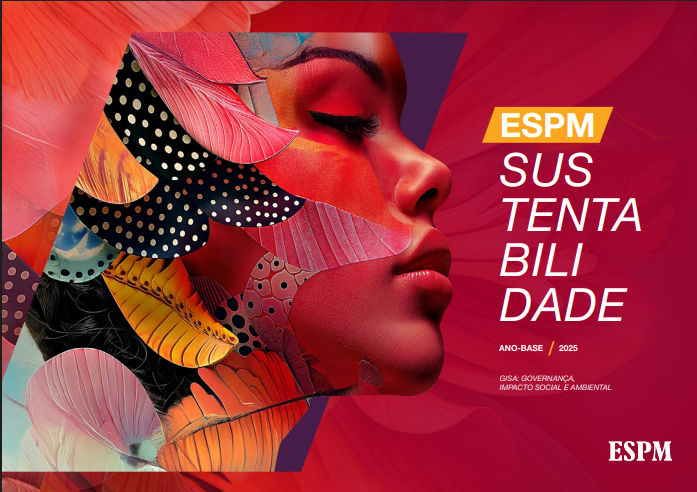
KICK develops ESPM's first Sustainability Report
The report, with 2025 data, uses the GRI Standards as a reference and relates to MEC assessments, the Ethos Indicators and the SDGs. See how it was developed and what it shows.
GRI expands its presence in Brazil: what changes in companies' sustainability reporting
With new climate, energy and biodiversity standards, regulatory changes and pressure on SMEs and supply chains, sustainability reporting enters a new phase in Brazil.
Letter at COP31 calls for political leadership to end deforestation by 2030
More than one hundred organizations, Indigenous peoples and research institutions call for an implementation process through 2030 and an international meeting in 2027. See what the letter says, the COP30 Roadmap and what changes for companies.